How a Fire Damage Insurance Claim Works in Miami
After a fire, call your insurer once everyone is safe and the fire department has cleared the building. Photograph the damage, keep receipts for urgent costs, and do not throw away damaged items until the adjuster has seen them. Frontline works with your insurance company and starts cleanup while the claim moves forward.
Recovering from a fire? We are open 24 hours and can start cleanup the same day.
Call now, any hour(305) 542-5253Start here if the fire was in the last day or two
These come before the claim itself.
- Make sure everyone, including pets, is accounted for and safe.
- Do not go back inside until the fire department says the building is clear.
- Ask the fire department for the incident report number. Your insurer will want it.
- Call your insurance company or agent and open the claim.
- Call us. We can board up, secure the property and begin soot and water cleanup.
Is fire damage covered by homeowners insurance?
Fire is one of the main events a standard homeowners policy is written for, and it usually includes smoke and the water used to put the fire out. Policies differ on limits, on how contents are valued, and on what the policy pays toward living somewhere else while the home is unusable.
Ask your insurer or adjuster how your policy treats the structure, your belongings and temporary housing. Those are separate parts of the policy and can have separate limits.
The claim, one stage at a time
Open the claim
Give the insurer the date, the cause if known, and the fire department report number. Write down your claim number and the name of the person you spoke to.
Protect what is left
Fire leaves a building open to weather and theft. Boarding up and tarping are the kind of reasonable steps policies expect, so keep the receipts.
Document the damage
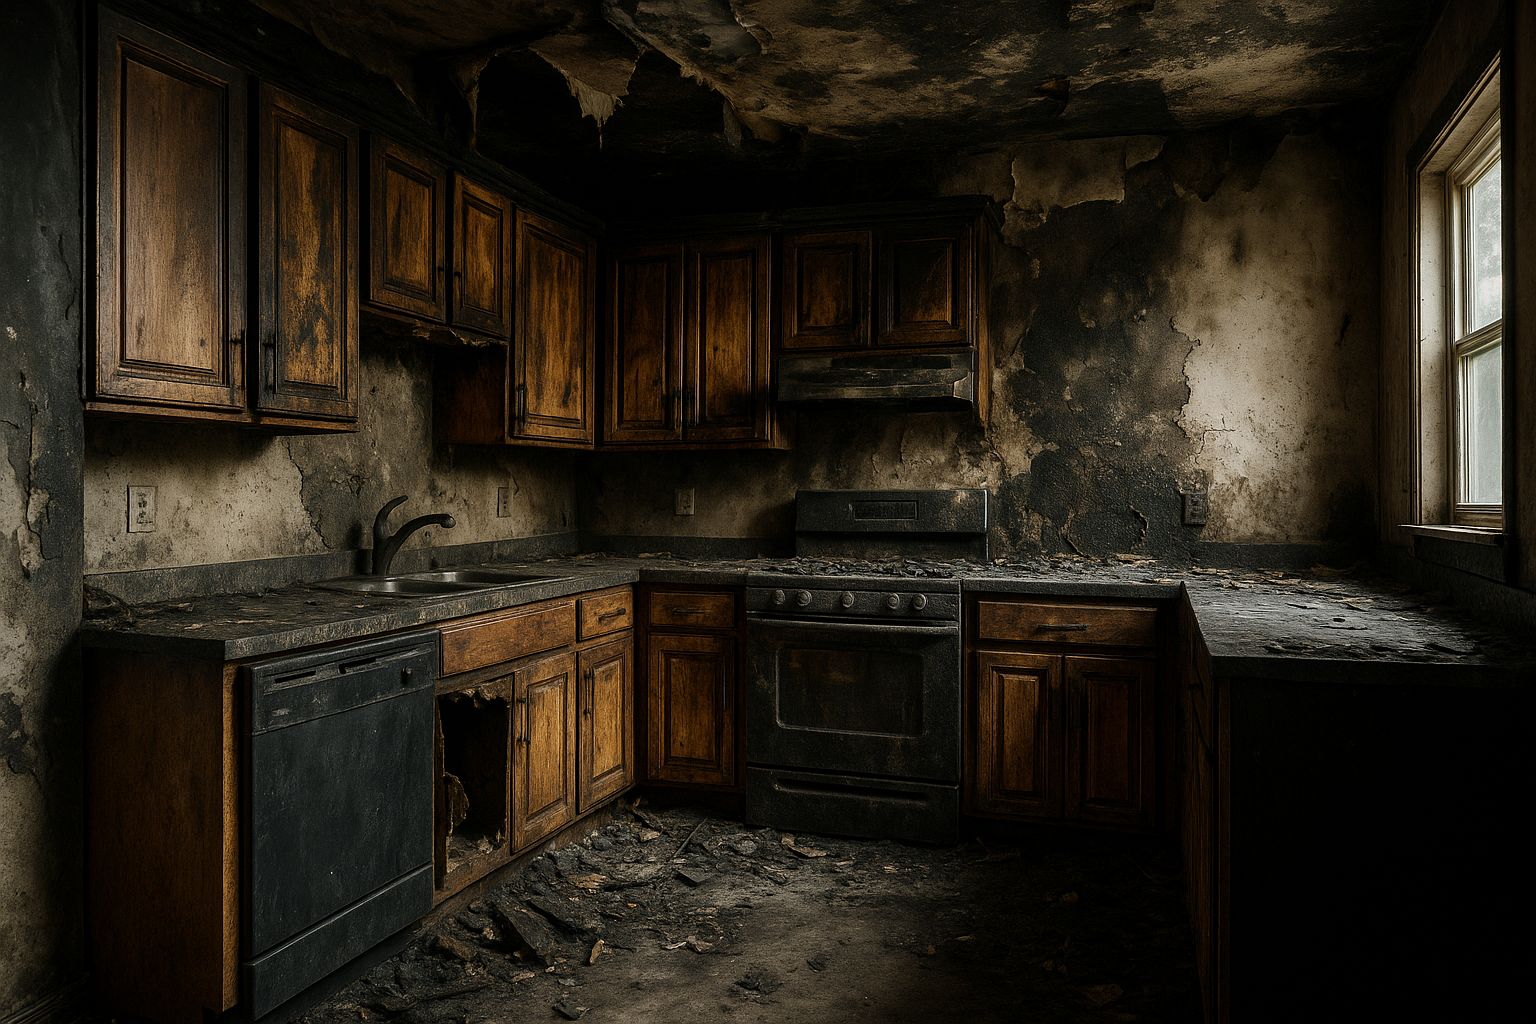
Photograph every room before cleanup, then keep photographing as work goes on. Include the rooms that look fine, because smoke travels.
Build the contents list
List what was damaged: item, age, and what you paid if you remember. Receipts, bank statements and old photos can all help fill gaps.
Work through the estimate
The adjuster reviews the loss and your insurer issues its estimate. A restoration scope of work gives you something specific to compare it to.
What should I keep and what can I throw away?
Keep until the adjuster sees it
Large damaged items, charred materials from the point of origin, and anything the fire department or insurer asks you to preserve. When in doubt, photograph it and ask first.
Usually discard
Food, medicine and cosmetics exposed to heat, smoke or fire-fighting water are generally not safe to use. Photograph and list them for the claim before they go.
How does Frontline handle the insurance paperwork?
Frontline Restoration bills insurance companies where your carrier allows it. Our crew photographs the loss, records the affected areas, and writes a scope of work that your carrier can review. Your deductible and any work the policy does not cover stay with you.
We do not decide what the insurer pays, and we will not promise an outcome. We keep the work and the documentation clear so the claim has what it needs.
When to call
- Smoke or soot has reached rooms away from the fire.
- The fire department used water and floors or walls are still wet.
- The building is open to the weather or cannot be locked.
- An odor lingers after the visible damage is cleaned.
- You want cleanup started before the adjuster visit.
What we do when you call
- Answer at any hour and ask about the fire, who has been through the property, and whether the building can be secured.
- Send a crew to assess soot, smoke and water, and to board up or tarp where needed.
- Start cleanup and drying, with photographs for your insurer at each stage.
- Work with the carrier and update you on progress and next steps.
Common questions
Is fire damage covered by homeowners insurance in Florida?
Fire is generally a covered event on a standard homeowners policy, and smoke and firefighting water damage are usually included. Limits, exclusions and contents valuation vary by policy. Read your declarations page and ask your insurer or adjuster what applies before you decide what to repair or replace.
How soon after a fire should I file a claim?
As soon as it is safe. Florida sets deadlines for reporting claims, and they have changed over the years, so do not wait. Calling promptly also lets the insurer approve emergency steps like boarding up and starts the paper trail while the damage is fresh.
Can I clean up before the adjuster arrives?
Photograph everything first. Then it is generally fine to protect the property, remove standing water and secure the building. Keep major damaged items until the adjuster has seen them, and tell your insurer what emergency work is being done so it does not cause a dispute later.
Does Frontline work with my insurance company?
Yes. Frontline Restoration works with insurance companies and provides photos, readings and a written scope of work for the claim. We cannot guarantee what a carrier will pay, since that depends on your policy and the adjuster. We do keep the documentation organized and complete.
Want a callback instead?
Send three quick answers. We will call you. For anything urgent, calling is faster.
Call now, any hour(305) 542-5253